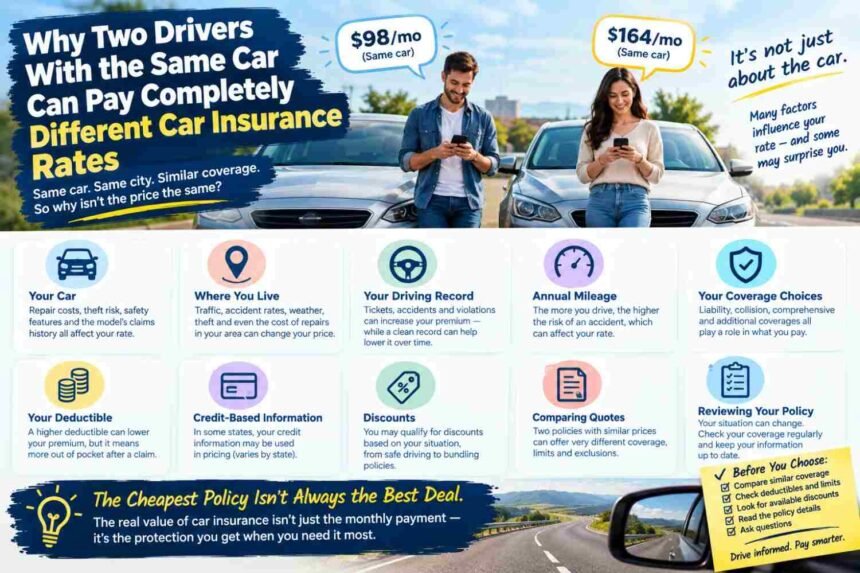
Two people can drive the same make and model, live in the same city, and have nearly identical insurance coverage—and still receive surprisingly different car insurance bills.
At first, that can make auto insurance seem random. One driver might pay hundreds of dollars less each year while both vehicles sit in the same neighborhood and face many of the same risks. But insurance companies are not pricing the car alone. They are trying to estimate how likely a particular driver is to file a claim and how expensive that claim could become.
That means the number on your insurance bill can be influenced by details you may not think have much to do with driving. Your driving record obviously matters, but so can your location, annual mileage, coverage choices, claims history, vehicle characteristics, and other underwriting factors. The exact rules and factors used can also differ by state and insurer.
Understanding what is behind your rate can make it easier to spot opportunities to save without automatically choosing the cheapest policy available.
Your Car Is Only One Piece of the Puzzle
Many drivers assume that insurance pricing begins and ends with the vehicle. A newer luxury SUV must cost more to insure than a basic sedan, right?
Not necessarily.
The vehicle does matter, but insurers can look at much more than its purchase price. Repair costs, theft frequency, safety features, crash-test performance, replacement-part prices, and the historical cost of claims involving that particular model can all affect the premium.
Two drivers might own identical vehicles but have very different insurance costs because their personal risk profiles are different. In other words, buying a cheaper car does not automatically guarantee a cheaper insurance policy.
This is one reason it can be useful to get insurance quotes before buying a vehicle rather than discovering the insurance cost afterward.
Your ZIP Code Can Make a Difference
Where your car is primarily kept can be just as important as what you drive.
Insurance companies may evaluate the risk associated with your location, including factors such as traffic density, accident patterns, theft, vandalism, weather exposure, and the cost of repairs in the surrounding area. A driver who moves from a low-traffic suburban area to a large metropolitan region could see a different premium even without changing vehicles.
The difference can become particularly noticeable when comparing urban and rural areas. A densely populated area may have more traffic collisions and more opportunities for theft or damage, while another area might have different risks, such as severe storms, flooding, or wildlife-related accidents.
That does not mean every insurer will price the same ZIP code the same way. Companies use different pricing models, so comparing quotes can still be important.
A Clean Driving Record Can Become Your Biggest Advantage
Your driving history is one of the most obvious factors insurers consider, but its impact can be larger than many drivers realize.
Tickets, at-fault accidents, serious violations, and other incidents can increase the perceived risk associated with a policyholder. A driver with several recent violations may be viewed very differently from someone who has maintained a clean record for years.
The good news is that a poor record does not necessarily define your insurance costs forever. The effect of an incident can change as time passes, depending on the insurer, the type of incident, and state regulations.
That makes safe driving more than just a way to avoid crashes. Over time, it can also help protect your insurance budget.
Annual Mileage Can Quietly Change Your Premium
One question on an insurance application that is easy to overlook is how much you drive.
Consider two identical cars. One is used for a short commute a few days a week, while the other travels long distances every day. The second vehicle spends substantially more time on the road, which generally creates more exposure to accidents.
Your estimated annual mileage can therefore become part of how an insurer evaluates your risk.
This is also why it is important to keep your information accurate. If your driving habits have changed significantly because you now work from home, have a shorter commute, or no longer use the vehicle for certain purposes, it may be worth asking your insurer whether the updated usage could affect your premium.
The Coverage You Choose Matters Just as Much
Sometimes the reason one driver pays more is much simpler: they bought more protection.
Car insurance policies can contain several different types of coverage, and each one addresses a different financial risk. Liability coverage helps protect against covered damage or injuries you cause to others. Collision coverage can help with covered damage to your own vehicle after a collision. Comprehensive coverage generally applies to certain non-collision losses, such as theft, vandalism, or qualifying weather-related damage.
Adding coverage, increasing limits, or selecting lower deductibles can increase the premium.
That does not mean those choices are bad. In fact, reducing coverage just to make the monthly bill smaller can leave you exposed to a much larger financial problem after an accident.
The goal is not simply to find the lowest premium. It is to find a level of protection that fits your finances and the risks you are actually willing to take.
The Deductible Trade-Off Is Easy to Misunderstand
Your deductible can have a noticeable effect on your premium.
Generally, choosing a higher deductible means you agree to pay more out of pocket before certain covered claims are paid, while a lower deductible usually means you take on less out-of-pocket cost when a covered loss occurs.
That can create an important trade-off.
Suppose lowering your deductible increases your premium every month. The extra cost might make sense if you do not have much cash available for an unexpected repair. On the other hand, a driver with a strong emergency fund might prefer a higher deductible in exchange for a potentially lower premium.
There is no universal “best” deductible. The right choice depends on your budget and how comfortably you could handle an unexpected expense.
Your Credit-Based Insurance Information May Matter in Some States
This is an area that often surprises drivers.
Some insurers in some states use credit-based insurance information as one factor in insurance pricing, where permitted by state law. The concept is not the same as simply looking at your traditional credit score for a loan. Insurers may use specific information to calculate an insurance-based risk score.
However, this practice is regulated differently across the country, and some states restrict or prohibit certain uses of credit information in auto insurance.
Because of those differences, a pricing factor that affects one driver in one state may not work the same way for someone elsewhere.
Discounts Can Be More Valuable Than a Driver Realizes
Insurance discounts can sometimes make a substantial difference, but many policyholders do not regularly check whether they still qualify.
Depending on the insurer and state, discounts may be available for things such as safe driving, multiple vehicles, bundling policies, certain safety features, defensive-driving courses, low mileage, or other qualifying circumstances.
The problem is that your situation can change while your policy stays the same.
You may have moved, changed your commute, added another vehicle, combined insurance with another household policy, or completed a qualifying course. If you never revisit your policy, you might miss discounts that could otherwise reduce your premium.
The Cheapest Quote Is Not Always the Cheapest Insurance
When comparing car insurance, it is tempting to focus on one number: the monthly payment.
But two policies with similar-looking prices can provide very different protection.
A cheaper policy might have lower liability limits, higher deductibles, fewer optional coverages, or exclusions that become important after a loss. Meanwhile, a slightly more expensive policy might provide considerably more financial protection.
This is why comparing quotes works best when you compare similar coverage levels. Otherwise, you may think one company is dramatically cheaper when you are actually comparing two different products.
Look beyond the premium and compare the limits, deductibles, coverage types, exclusions, and insurer-specific benefits that matter to you.
Why Shopping Around Can Be Worth It
Insurance companies do not all calculate risk in exactly the same way.
One insurer might place more emphasis on a particular characteristic, while another may offer a more favorable price for the same driver. That means your current premium is not necessarily the market price for your profile.
This is one of the most important reasons to compare quotes periodically.
Even if nothing has changed about your driving, your insurer’s pricing model, claims experience, underwriting rules, or overall business strategy can change. Another company could potentially offer a better combination of price and coverage.
You do not necessarily need to change insurers every year. But knowing what alternatives are available can help you decide whether your current policy remains competitive.
Before You Cut Coverage, Look at the Bigger Picture
A lower insurance bill can feel like an immediate win, especially when household expenses are rising. But cutting coverage without understanding the potential consequences can create a much bigger financial burden later.
Think about what would happen if your car were severely damaged, stolen, or involved in a serious accident. Could you comfortably replace the vehicle? Could you cover a large deductible? Would your liability limits provide enough protection for a major claim?
Those questions can be uncomfortable, but they are often more useful than simply asking, “How can I get my premium lower?”
Sometimes the smarter way to save money is not to eliminate protection but to improve your overall insurance shopping strategy.
The Number on Your Bill Is Not the Whole Story
Car insurance pricing can look confusing because a premium is the final result of many different inputs rather than a simple price attached to a vehicle.
Your driving history, where you live, how much you drive, the type of vehicle you own, your selected coverage, deductible, claims history, discounts, and other factors can all play a role—and the importance of each factor can vary by insurer and state.
That is why two people with the same car can open their mail or insurance app and see completely different numbers.
Instead of assuming your premium is fixed, treat it as something worth reviewing. Keep your policy information accurate, understand what you are actually paying for, check available discounts, and compare quotes using equivalent coverage.
The cheapest policy may not always be the best deal. But understanding why your rate is what it is can put you in a much better position to find the right balance between protection and cost.